Blog

  • You Know How Much You Invest Every Month. But Do You Know If It Is Enough?

    When I speak to clients during financial planning, a few questions come up again and again. I thought it may be useful to share how we can look at these questions because many investors may be wondering the same thing
    .

    Thanks for reading! Subscribe for free to receive new posts and support my work.

    “I am investing ₹50,000 every month. Is that enough?”

    Another common question I hear is: “I increase my SIPs by 10% every year. Is that good enough?”

    These sound like simple questions. But ₹50,000, ₹1 lakh or a 10% annual increase tell us very little by themselves.

    The more useful question is: Enough for what?

    The amount alone tells us very little

    Suppose I tell you: “I drive 50 kilometres every day. Is that enough?”

    You cannot answer unless you know where I am trying to go and when I need to reach there.

    If the destination is nearby, it may be more than enough. If it is 1,000 kilometres away and I need to reach tomorrow, clearly it is not.

    Investing works much the same way.

    ₹50,000 a month may be enough for one person and nowhere near enough for another. It depends on the goals you are trying to fund, how much those goals may require, when the money will be needed and how much you have already accumulated.

    That is why these two statements are not the same: “I am investing regularly” and “I am on track for my goals.”

    You can invest diligently for years and still discover later that the amount was not enough.

    There is no magic SIP amount

    Naturally, investors look for a rule.

    “How much of my salary should I invest?”

    “Is 20% enough?”

    “Should I increase my SIP by 10% every year?”

    Such numbers can be useful as broad assumptions or starting points. But they should not become financial rules that we follow mechanically.

    There is no universal minimum or maximum investment amount.

    Two people earning the same income may need to invest very different amounts. One may already have substantial investments and many years available. Another may have started later or have larger financial commitments.

    So the right amount cannot come from a standard percentage. It has to come from your goals, your present financial position and the time available to you.

    There is no compulsory 10% step-up either

    The same applies to increasing investments every year.

    A 10% annual SIP increase is commonly used in financial projections. But that does not mean everyone should increase investments by exactly 10%.

    If your income rises substantially and you can comfortably increase your investments by 20%, 25% or 30%, why stop at 10% simply because a calculator assumes it?

    And there may be another year when even a 10% increase is not practical.

    A 10% SIP step-up is an assumption. It is not a financial rule.

    Once normal expenses, near-term requirements and necessary liquidity are taken care of, invest the genuine surplus available to you. If your ability to invest increases, increase your investments.

    Meeting your goals should not become a ceiling

    Suppose your financial plan indicates that a certain monthly investment should reasonably put your important goals on track.

    Does that mean you should stop investing anything beyond that amount? Not necessarily.

    Meeting financial goals is important, but it need not be the end of the journey.

    If you have additional genuine surplus, that money can continue working for you. Over time, it can build wealth, create a larger financial cushion and give you more choices later in life.

    So the amount required for your goals may tell you what is needed for the plan.

    It should not automatically become the maximum you are willing to invest.

    This is why rigid rules such as “I already invest 20% of my income, so I am saving enough” can be misleading.

    But what if you are already investing as much as you can?

    Now consider the opposite situation.

    You are already investing the genuine surplus available to you, but the amount may still not be enough for your goals. It means there is a gap that needs to be recognised.

    Over time, you may be able to close it by investing more as your income rises, giving the goal more time or adjusting some expectations.

    Start with the purpose, not the product

    This connects with a theme running through my earlier articles.

    In “Should You Invest in an International Fund? Try This Test First”, the question was whether an investment had a purpose in the portfolio.

    In “You Don’t Drive an Entire Journey in One Gear. Then Why Invest That Way?”, I discussed why money needed at different stages of our financial journey should not all be invested in the same way.

    The same principle applies here.

    Before asking which mutual fund should receive the next SIP, first ask whether the amount being invested is enough for what you are trying to achieve. The product comes later.

    One final thought

    There is no universal answer to how much we should invest. ₹20,000 may be enough for one person’s goals and ₹2 lakh may not be enough for another’s.

    What matters first is whether what you are investing is reasonably putting your important financial goals on track.

    If it is not, recognise the gap rather than make it disappear with a higher return assumption.

    And if your goals are comfortably on track and you can invest more, don’t let an arbitrary savings percentage become a stopping point. Let that additional money continue working for you and building wealth.

    So instead of asking: “Am I investing a good amount?”

    ask: “Is what I am investing enough for my goals?”

    And once the answer is yes, let whatever more you can invest continue working for your future and create wealth for you.

    Mahesh Kumar K is a SEBI Registered Investment Adviser and Principal Adviser at ClearPath Wealth. He is a member of Fee-only India. This article is for general education and does not constitute personalised investment advice.
    Thanks for reading! Subscribe for free to receive new posts and support my work.

  • Using AI for Your Money Decisions? Ask These 4 Questions First

    AI can help us think better about money. But only if we know what to question before acting.

    Thanks for reading! Subscribe for free to receive new posts and support my work.

    In recent months, I have noticed more investors using AI for money decisions.

    Some use it to understand mutual funds. Some use it to compare investment options. Some ask whether they should buy gold, increase equity, prepay a loan or change their portfolio.

    I think this is useful.

    AI can explain concepts, organise information and run calculations much faster than most of us can do manually. It can also help us see alternatives that we may not have considered.

    But a money decision is not just an answer on a screen.

    We may be deciding what to do with money built over many years of work and saving. A suggestion that looks sensible in a chat window can affect retirement, children’s education, a house purchase or peace of mind many years later.

    So the real problem is not whether AI can give an answer. It can.

    The harder problem is whether we know how to question that answer.

    A convincing answer can still be incomplete

    Consider a simple question: “Which are the best mutual funds for me?”

    Ask an AI tool this question and it may quickly give you a neat list of funds, categories, returns and reasons for choosing them. The answer may look very convincing.

    But has every return been checked from a reliable source? Is the comparison fair? Is the five-year return actually a live track record? Does the fund even belong in your portfolio?

    A wrong number and a correct number can look exactly the same when they are presented confidently. That is the uncomfortable part.

    The dangerous answer is not always an obviously wrong one. It may be a mostly sensible answer with one important gap. And that gap may be enough to change the decision.

    To challenge an AI answer, we first need to know what requires checking.

    The question may matter more than the answer

    Many investors start with the investment.

    “Which fund is best?”

    “Should I invest in gold?”

    “Should I increase equity?”

    These are common questions. But they may not always be the right first questions.

    A good investment can still be wrong for a particular purpose.

    For example, equity may be a good long-term asset. But if the money is needed next year, that fact alone does not make equity suitable. Gold may have a role in some portfolios, but that does not mean every investor needs it. A mutual fund may have strong past returns, but that does not automatically mean it fills a gap in your financial plan.

    In one of my earlier articles, I had discussed that money needed at different times has different jobs and should not all be invested in the same way. The same idea applies here.

    AI may help us find an investment. But before that, we need to ask whether we need that investment at all.

    Often, the most valuable part of a money decision is not finding the answer. It is making sure we are solving the right problem.

    AI knows what you tell it

    Suppose an investor tells AI: “I am 40, have a stable income, can invest for ten years and have a moderately aggressive risk profile.”

    That sounds like useful information.

    But what does “moderately aggressive” really mean?

    Someone may say he can tolerate a 25% fall in equity. When the market actually falls 10%, his behaviour may say something else. What we say about risk and how we behave with real money are not always the same.

    There may be other missing details too.

    Is there enough emergency money? Are there near-term goals? Is there a large home loan? Are the existing investments already equity-heavy? Is the investor likely to stop SIPs during a bad market?

    AI can analyse the information we give it.

    The bigger risk is the information we do not give because we do not realise it matters. This is where financial decisions become different from simple calculations.

    Should you prepay more of your home loan, invest more for retirement or keep more money available for family needs?

    AI can compare the numbers. But some money decisions do not have one perfect mathematical answer. They involve priorities, uncertainty and compromise.

    The final answer has to work in real life, not only in a spreadsheet.

    So where is AI genuinely useful?

    AI can help organise financial information, explain investment concepts, compare alternatives, run calculations and test assumptions. It can also help us ask better questions.

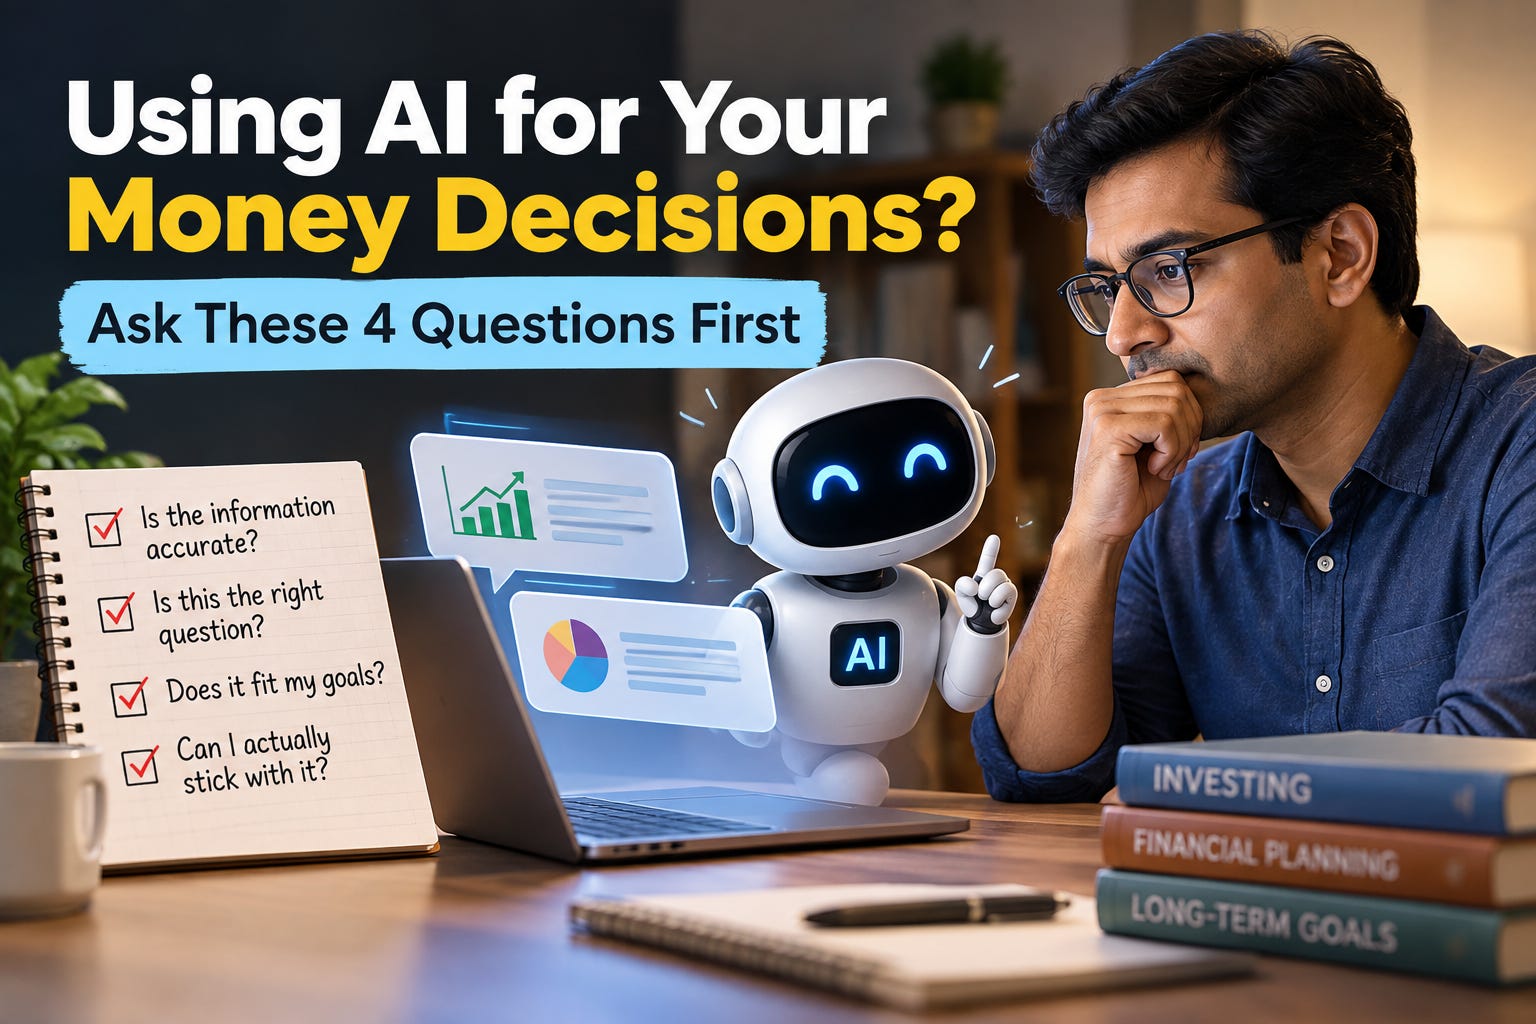
    Four questions before acting on an AI financial answer

    1. Do I know whether the important facts and numbers are correct?
    If not, verify them from a reliable source.

    2. Do I know what assumptions AI has made and what important information may be missing?
    A precise-looking answer can change completely when one assumption changes.

    3. Is AI answering the question I asked, or the money question I actually need to solve?
    “Which fund is best?” and “What does my portfolio need?” are very different questions.

    4. Can I actually follow this decision when circumstances become difficult?
    A decision has to work not only when markets are calm, but also when they are uncomfortable.

    One final thought

    AI is making information, explanations and calculations available in seconds. That is valuable. But when answers become easier to obtain, the quality of the decision becomes even more important.

    The real opportunity is not to hand our money decisions over to AI. It is to use AI to question more, understand more and think more clearly before we act.

    For money built over years of work and saving, that difference matters.


    Mahesh Kumar K is a SEBI Registered Investment Adviser and Principal Adviser at ClearPath Wealth. He is a member of Fee-only India. This article is for general education and does not constitute personalised investment advice.
    Thanks for reading! Subscribe for free to receive new posts and support my work.

  • The Bhagavad Gita and Your Portfolio

    The very first verse of the Bhagavad Gita begins with a question.

    Dhritarashtra, who cannot see the battlefield himself, asks Sanjaya: What is happening out there? (Chapter 1, Verse 1)

    It is a question many of us quietly ask on a difficult day in the market. We check the news. We check our portfolio. And often, the more we look, the less clear things become — because what we are really struggling with is not the market. It is our own reaction to it.

    Generations of commentators have read the Gita’s battlefield as something deeper — an inner battle between what we know is right and what our fears and impulses push us toward.

    The war is never really in the market. It is in our own head.

    We already know. So why is it so hard?

    Most of us already know the sensible things. Stay invested for the long term. Do not panic when markets fall. Do not chase whatever did well last year.

    Then markets fall 20%. And somehow, the long-term investor wants to pause his SIPs “until things settle down.” The disciplined investor finds himself checking his portfolio three times a day.

    Knowing what to do and actually doing it with real money — these turn out to be very different things.

    Arjuna faced the same struggle. He knew what needed to be done. But when the moment came, he could not move — his limbs failed him, his bow slipped from his hand (Chapter 1, Verses 28–30). Fear and worry about the outcome had quietly taken over.

    Krishna did not give him a new strategy. He simply helped Arjuna see what was really stopping him — his attachment to the outcome.

    Our responsibility is to the action; the result is not entirely ours to command. (Chapter 2, Verse 47)

    For us as investors, this means something practical. Our job is to understand what each part of our money is meant to do. In my earlier article, You Don’t Drive an Entire Journey in One Gear — Then Why Invest That Way?, I compared investments to different gears for different roads. We choose suitable investments, take risks we can genuinely live with and review when facts change.

    That is our part. It is important, and it is real. But we cannot decide what return the market will give us.

    The return is uncertain. The ride is part of the journey. We choose the gear. We do not get to choose what lies ahead on the road.

    Being the same investor in good times and difficult times

    When our portfolio rises 30%, we feel we made great decisions. When it falls 20%, we feel something has gone wrong. But the investment was the same. Only the price moved.

    Before sending Arjuna into battle, Krishna gives him a specific instruction: treat pleasure and pain the same. Gain and loss the same. Victory and difficulty the same. And then give it your best (Chapter 2, Verse 38).

    And then he says something even more striking — this evenness of mind is not something that comes after we become skilled. It is itself the skill. It is itself the discipline (Chapter 2, Verse 48).

    Think about what that means for investing.

    The real work is not just finding the perfect fund. The real work is being the same investor in March 2020 that we were in January 2020. It is continuing the same SIP in a falling market that we happily started in a rising one.

    Staying steady through both the good stretches and the difficult ones — that is the real work of investing.

    One question can help when the market shakes us: What actually changed — the facts or my feelings?

    We do not dig up a seed every month to check whether its roots are growing. It grows because we gave it the right conditions and then let it be. Investing asks the same of us.

    How we quietly lose our way

    There is a moment in the Gita where Krishna explains to Arjuna how good judgment falls apart — step by quiet step (Chapter 2, Verses 62–63).

    It starts with dwelling on something desirable. From that, attachment grows. From attachment, desire builds. When desire is not fulfilled, anger follows. From anger comes delusion. And from delusion, judgment collapses entirely.

    A fund returned 40% last year. We hear friends talk about it. Slowly, we start wanting it — not because our plan needs it, but because the result is attractive. That is the first step. We invest. Now we are holding not just a fund but an expectation. That is the attachment. The fund does not repeat that performance. Disappointment builds. Eventually we sell and move to whatever is doing well now. The cycle begins again.

    In my earlier article, Should You Invest in an International Fund? Try This Test First, I suggested a simple test: if the recent return chart were hidden, would we still want the investment?

    Recognising where we are in this chain, before frustration takes over, may save us from many bad decisions with our money.

    Why we invest at all

    If markets are uncertain and even our own minds work against us sometimes — why invest at all?

    Because we believe that despite wars, recessions, pandemics and crashes, over time, businesses grow, economies expand and markets reflect that growth. Every decade has given investors a reason to sell everything. And every decade, the investor who stayed has been rewarded.

    The Gita tells us something that fits beautifully here: whatever is happening is happening for good and is part of a larger will. Not everything will feel good in the moment. But the direction is forward.

    We do not invest because we expect an easy journey. We invest because the future we are building is worth it.

    One final thought

    The Bhagavad Gita does not tell us which mutual fund to buy or what return to expect. But it tells us something about ourselves that no factsheet or calculator ever will.

    That the real battle is in our mind, not in the market. That our job is the action — choosing well, investing carefully, staying the course — and the result will follow its own timetable. That steadiness through both good times and difficult times is not a bonus that comes later — it is itself the discipline. That wanting quietly becomes attachment, then anger, then broken judgment — and seeing this chain early can save us from our worst decisions. And that whatever is happening is happening for good and is part of a larger will.

    Do what is ours to do — earn, save, invest and plan — and do it as well as we can.

    A saint once said, “Everything in future will improve if you are making spiritual effort now.” For an investor, the parallel is simple: our tomorrows are being built, quietly and steadily, by the right work we do today.

    Our money should work for our life. Our life should not quietly start working for our money.

  • You Don’t Drive an Entire Journey in One Gear. Then Why Invest That Way?

    When I review investment portfolios, I often see two very different kinds of investors. Some have most of their money in fixed deposits, savings accounts and other very safe investments. Others have gone almost entirely the other way, with most of their wealth in equity mutual funds, stocks or other growth-oriented investments.

    These approaches look completely different, but they can create the same problem: almost all the money is travelling in one gear. That can make the financial journey unnecessarily difficult and, at times, risky.

    Different roads need different gears

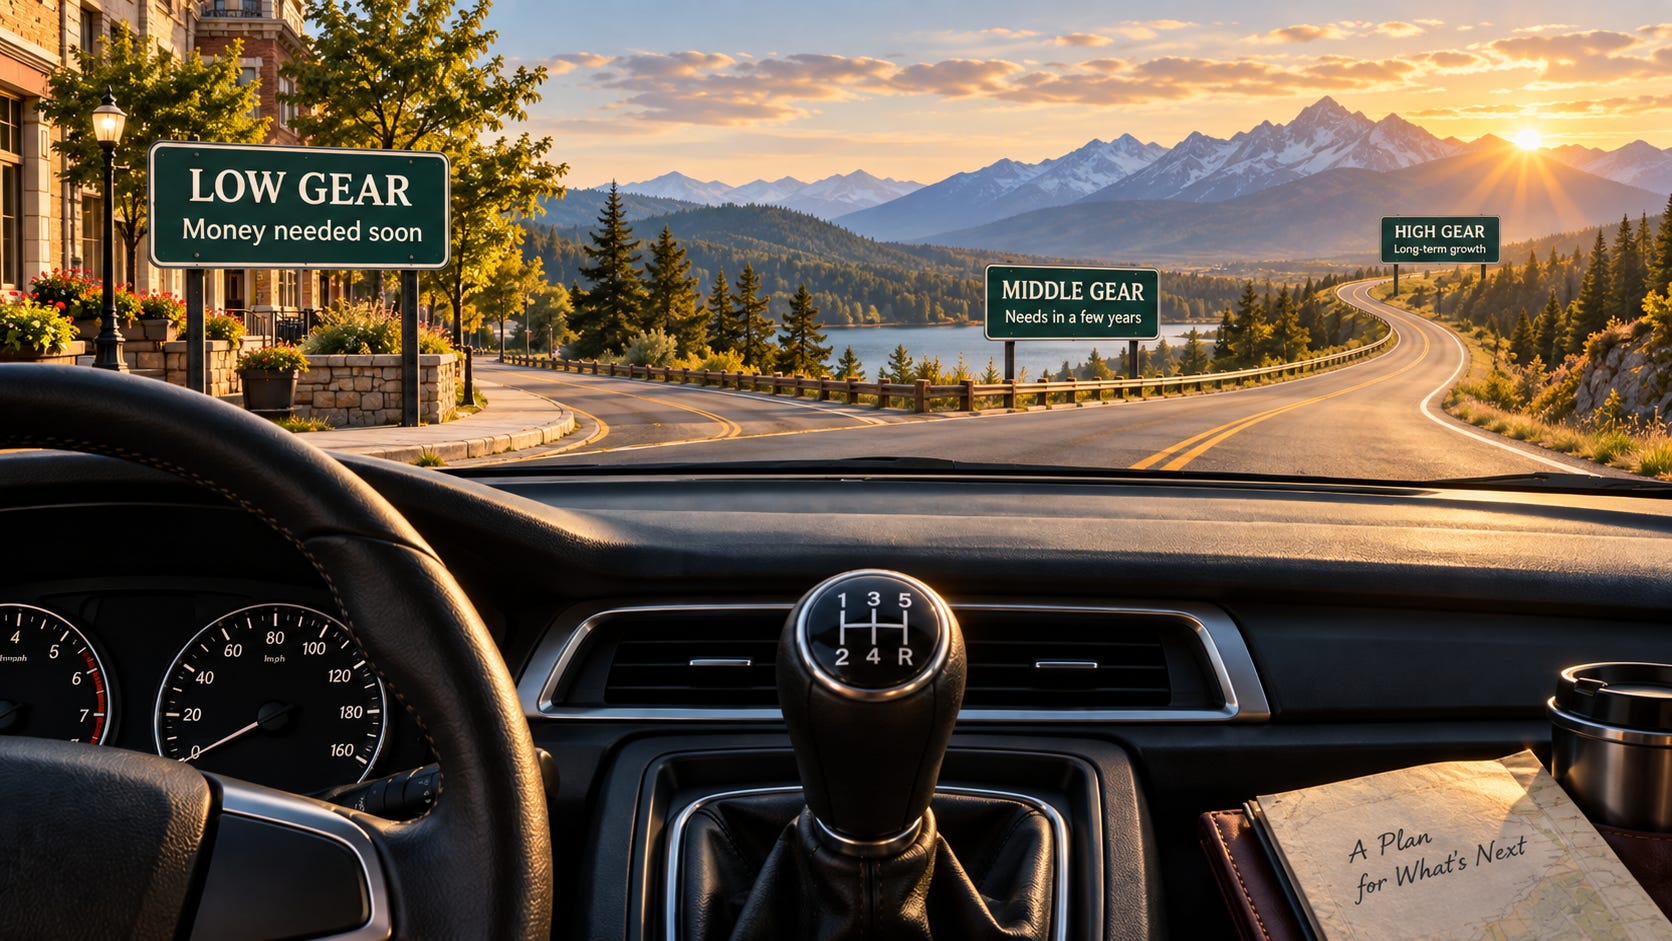
    Think about a long road journey. There are stretches where you need control, stretches where you can move comfortably, and open roads where you can travel faster. You do not remain in the lowest gear for the whole journey, but you do not stay in the highest gear everywhere either. The right gear depends on the road ahead.

    Money works in much the same way. Some may be needed soon, some a few years later, and some may not be needed for five years or more. For retirees, the long-term portion may have an even longer runway. The exact number matters less than the principle: money needed at different times should not all travel in the same investment gear.

    The lower gear: when safety and access matter most

    Money that may be required soon has one primary job: it should be available when you need it. Here, liquidity and stability matter more than squeezing out the highest possible return. Savings accounts, fixed deposits or other suitable low-volatility investments can play this role depending on the purpose.

    It can be tempting to say, “Equity should earn more.” Perhaps. If your child’s college fee is due next year, the market does not know that. If you need money for a house purchase six months from now, equity markets will not become less volatile because your payment date is approaching. For this part of the portfolio, certainty can be more valuable than return.

    But staying in the lower gear forever creates another risk. Money meant for goals several years away may not grow enough if it remains permanently in very low-return investments. Inflation keeps increasing the cost of the destination while the portfolio moves slowly toward it. The ride may feel smooth, but you may still fall short.

    The higher gear: when time allows growth

    Now consider money that may not be needed for five years or more. Here, the job is different: there is more time to absorb market ups and downs in pursuit of stronger long-term growth.

    This is where equity and other suitable growth assets can play an important role. But one condition matters enormously: the money must genuinely have a long runway.

    High gear works because the road is long. It does not mean high gear is always better.

    The problem appears when almost everything is in high gear. If an important requirement arrives during a sharp market fall, the investor may have to sell equity after it has fallen.

    The danger is not simply that equity can fall. The danger is needing to sell equity when it has fallen.

    Markets recover on their own timetable; our financial goals follow ours. When those timetables collide, a portfolio that looked efficient during good markets can suddenly become fragile.

    I discussed a related idea in my earlier Freefincal article, “Should You Invest in an International Fund? Try This Test First”. There too, the question was whether an investment actually had a role in the portfolio. The same principle applies here: first understand when the money may be needed, then choose the investment.

    The missing middle gear

    Between money required soon and money that can remain invested for the longer term lies a large part of real financial life. This is where a middle gear becomes useful: a part of the portfolio designed to balance stability with reasonable growth. Investors often behave as if money has only two choices: very safe or very aggressive. Financial life is rarely that binary.

    The middle layer also performs another important job. If money needed over the next few years is positioned appropriately, you are less likely to disturb long-term growth investments during a bad market. In that sense, the safer parts of the portfolio do more than protect themselves; they can protect the growth portfolio from being sold at the wrong time.

    Your portfolio should not ask one investment to do three different jobs

    This is the larger idea: some money needs to remain liquid and stable. Some needs a balance between stability and growth. Some needs to compound for the longer term.

    No single investment can optimise all three jobs at the same time.

    That is why “Which investment gives the highest return?” should not be the only question. Equally important is whether the investment is suitable for when the money will actually be needed.

    One final thought

    A good financial journey does not require us to predict every difficult road ahead. It requires a portfolio that can handle different roads when they arrive.

    The goal is not to stay permanently safe, nor is it to remain permanently aggressive. The goal is to have the right money in the right gear for the road ahead.

    You would not drive an entire road journey in one gear. Your portfolio should also have different gears for different parts of your financial journey.


    Mahesh Kumar K is a SEBI Registered Investment Adviser and Principal Adviser at ClearPath Wealth (www.clearpathwealth.in). He is a member of Fee-only India. This article is for general education and does not constitute personalised investment advice.